Purpose
Investors frequently enter transactions in which they make significant but not controlling investments in an entity. When investments made in common stock provide the investor with significant influence over the investee, an investor should apply the equity method of accounting unless the investor elects a fair value option for the investment. The equity method of accounting would also be used for investments in a joint venture.
This publication provides an overview of the key accounting considerations and implementation matters relating to ASC 323 (Investments – Equity Method and Joint Ventures). The technical views and accounting positions on the framework keep enhancing depending on carrying out further technical evaluations and their outcomes.
We sincerely hope you find this quick reference guide informative in identifying and evaluating the issues related to the accounting for equity method investments. We will be happy to participate in any discussions required to clarify our views enclosed in the attached publication. We look forward to hearing from you.
Background
Equity investments made by investors represent an ownership interest (for example, common stock, preferred stock, or other capital stock) in an entity, and may be made in various type of legal entities, such as corporations, limited liability partnerships or corporations. Equity investments may be accounted for as a controlled subsidiary, equity method investment, or financial asset.
The accounting for an equity investment by an investor depends on the degree of influence that can be exercised over the investee. An investor who is holding a controlling financial interest (either directly or indirectly) in another entity is required to consolidate that entity pursuant to either the variable interest entity (VIE) or voting interest entity (VOE) consolidation model, as per the principles of ASC 810, Consolidation. On the other hand, if it is concluded that an investor does not have a controlling financial interest, it should determine whether the equity method of accounting as prescribed by ASC 323, Investments – Equity Method and Joint Ventures is applicable,
ASC 323 provides guidance on the accounting for investments under the equity method. Investments within the scope of the equity method include:
- Investments in either common stock and/or in-substance common stock (for e.g. investment with a non-substantive liquidation preference or without a stated liquidation preference over the investee’s common stock may be substantially similar to common stock) of corporate entities,
- Investments in entities like limited liability companies, unincorporated joint ventures, and partnerships.
The equity method is applicable if these investments allow the investor to exercise significant influence over the investee. Moreover, the equity method must be applied to a limited partner’s interest unless the interest held by the limited partner is so minor that the limited partner has virtually no influence over the partnership’s operating and financial policies.
To view the flowchart summarizing the accounting for equity investments, download the pdf.
Summary of Topic
Existence of Significant influence- Criteria for applying Equity method of accounting
Existence of an ability to exercise significant influence over the operating and financial policies of the investee is a primary condition for applying the equity method. Determining significant influence requires evaluating the facts and circumstances related to each investment, and such an assessment should be made on an ongoing basis.
To view the table summarizing the voting percentages assumed to demonstrate the existence of significant influence:, download the pdf.
Scope exceptions
The equity method of accounting generally does not apply to:
- An investment accounted for in accordance with Subtopic 815-10, Derivatives and Hedging
- An investment in common stock held by a non-business entity, such as an estate, trust, or individual.
- An investment in common stock within the scope of Topic 810,
- Except as discussed in paragraph 946-323-45-2, an investment held by an investment company within the scope of Topic 946.
Identification of Joint Venture
The joint venture is a legal entity, which must have all the following characteristics:
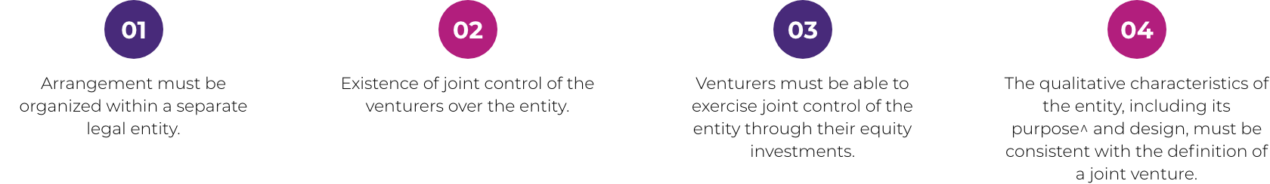
^ Purpose of the entity should be sharing risks and rewards to develop a new market, product or technology; combining complementary technological knowledge; or pooling resources to develop production or other facilities.
Initial recognition and measurement of Equity method investment
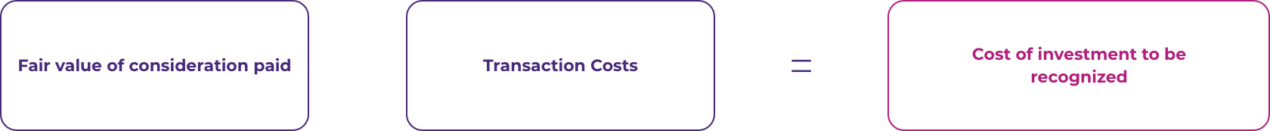
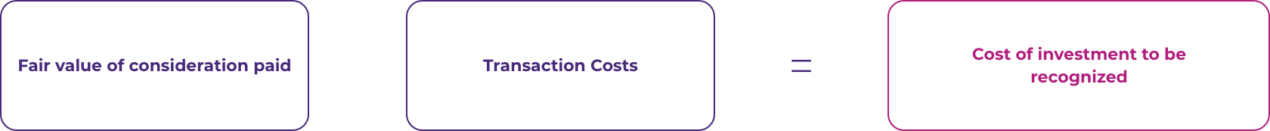
An investor is required to measure an equity method investment initially at cost. Consequently, equity method investments generally are recognized using a cost accumulation model in which the investment is recognized based on the cost to the investor, which is generally based on the fair value of the consideration paid which includes transaction costs as well. Costs incurred by an investor forming part of the cost of an equity method investment should be limited to direct costs of acquiring the equity method investment.
Subsequent measurement of Equity method investment
Under the equity method of accounting, investors’ share of the earnings or losses of an investee shall be recognized in the periods for which they are reported by the investee in its financial statements rather than in the period in which the dividend is declared by an investee.
Under the equity method of accounting, investors’ share of the earnings or losses of an investee shall be recognized in the periods for which they are reported by the investee in its financial statements rather than in the period in which the dividend is declared by an investee.