

20, June 2024
MYTH #1
Myth: A comprehensive TPRM program is only essential for organizations with thousands of third parties.
Reality: Even a single vulnerability in your third-party ecosystem — extending to fourth and nth parties — can jeopardize your entire supply chain. You are only as secure as your weakest link
How to Address It: Implement a “fit-for-purpose” TPRM program to right-size your efforts and resources and address the risk of an evolving threat landscape.
MYTH #2
Myth: All third parties present the same level of risk
Reality: Third parties differ significantly in risk exposure, data sensitivity, and operational criticality. A one-size-fits-all approach is ineffective
How to Address It: Implement a risk-based approach for a more effective and efficient TPRM program
MYTH #3
Myth: More assessments lead to a stronger TPRM program.
Reality: Many organizations over-engineer TPRM assessments without realizing actual risk reduction.
How to Address It: Optimize the assessments by adopting a combination of modernized and intelligent automation techniques for risk identification
MYTH #4
Myth: Traditional risk assessments are an essential pillar of effective TPRM.
Reality: In risk posture, the likelihood and impact of an incident are dynamic through a third-party lifecycle. Over-reliance on a one-time snapshot gives the organization a false sense of security.
How to Address It: Adopt a data-driven algorithmic approach combining internal and external parameters to ensure ongoing visibility and reduce efforts and reliance on manual risk assessments
MYTH #5
Myth: Rigorous risk assessments lead to a robust TPRM
Reality: Risk mitigation is often overlooked, while risk identification gets hyper attention in the TPRM lifecycle
How to Address It: Focus more on ‘act’ than ‘assess’ to reduce the overall risk by utilizing previous issues to address fundamental root causes.
MYTH #6
Myth: TPRM is independent of procurement, IT, or information security
Reality: Risk mitigation is often overlooked, while risk identification gets hyper attention in the TPRM lifecycle.
How to Address It: Identify clear RACI, including the level of involvement throughout the third-party lifecycle management, and use hyper-automation to reduce
coordination debt.
MYTH #7
Myth: Only technology third parties are relevant for TPRM.
Reality: While cybersecurity is a significant concern, TPRM involves compliance, operational risk, financialstability, legal risks, and service continuity
How to Address It:Consider all significant risk areas (relevant to your organization) and the 100% third-party ecosystem while defining the building blocks of your TPRM program.
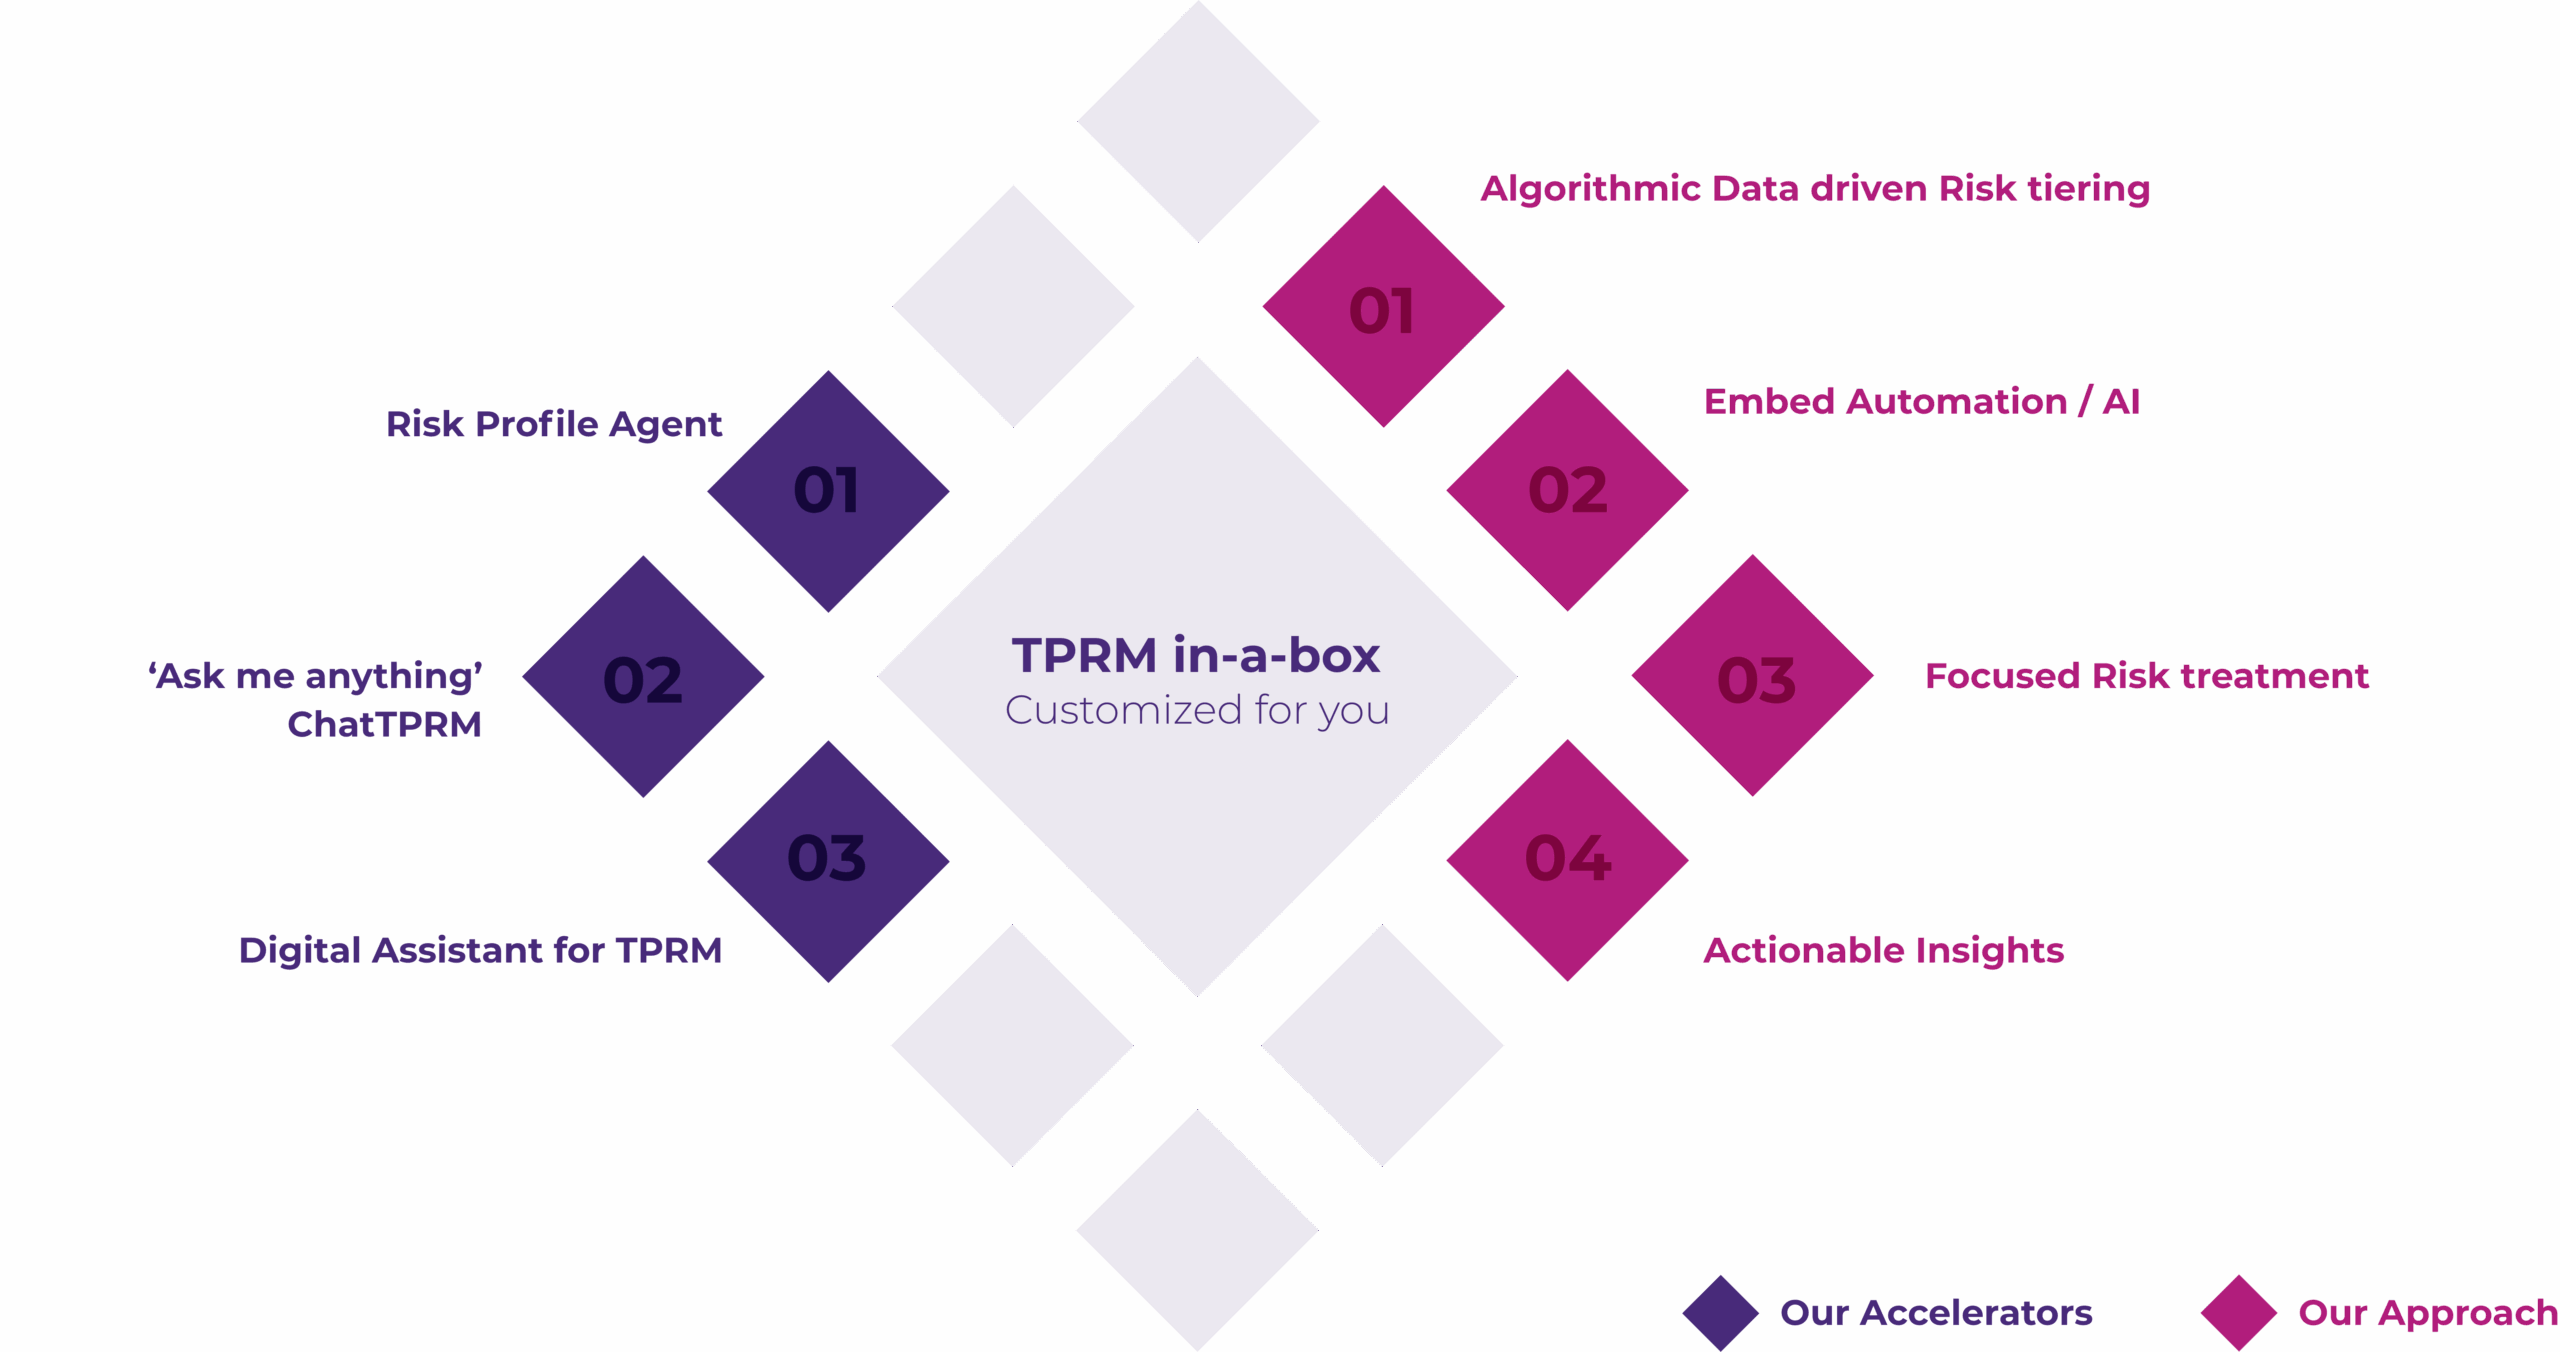
TPRM IN-A-BOX
At Uniqus, we specialize in helping you establish, manage, and optimize a modernized, fit-for-purpose Third-Party Risk Management (TPRM) program.
Foundational Pillars
Visibility: 100% coverage for the third-party ecosystem
Efficiency: 40% efficiency improvement in the first
Consistency: Improved consistency across the life-cycle
Risk reduction: Proactive risk reduction for early interventions
Topics in this article
Related
Uniqus Insights
Follow the contracts
THE QUESTION A dollar of customer spend on artificial intelligence (AI) model inference can show up as revenue in one company and as a net fee in another, with nothing different about the service that was actually delivered. Both presentations...
Uniqus Insights
Cannabis Rescheduling and Internal Revenue Code Section 280E
Executive Summary Federal cannabis policy now has two distinct tracks. Effective 28 April 2026, a Department of Justice final rule placed Food and Drug Administration (FDA)-approved drug products containing marijuana and marijuana covered by a state medical marijuana license in...
Early Impressions
FASB’s Accounting Standards Update ASU 2026-03
Executive Summary On September 9, 2026, the Financial Accounting Standards Board (FASB) issued Accounting Standards Update (ASU) 2026-03, Fair Value Measurement (Topic 820): Investment Companies with Equity Securities Subject to Contractual Sale Restrictions. The update introduces a narrow exception to...
